Understanding your breakeven point
Most business owners can tell you what they turned over last year. Far fewer can tell you what they need to turn over next month before they can start making a profit – and even fewer know how that number changes throughout the year. That number is your breakeven point: the amount your business needs to earn to cover its costs before it starts making profit. Understanding it can help you make better decisions about your business and your cash flow.
“Almost every owner I sit down with can tell me last year’s turnover. Very few can tell me what next month costs them just to open the doors. It’s the month-by-month number that changes decisions – the annual one just gets filed.”
Andrew Holmes | Director
But breaking even on paper isn’t the same as having cash in the bank.
There are two versions: your textbook breakeven and your cash breakeven.
What is your breakeven point?
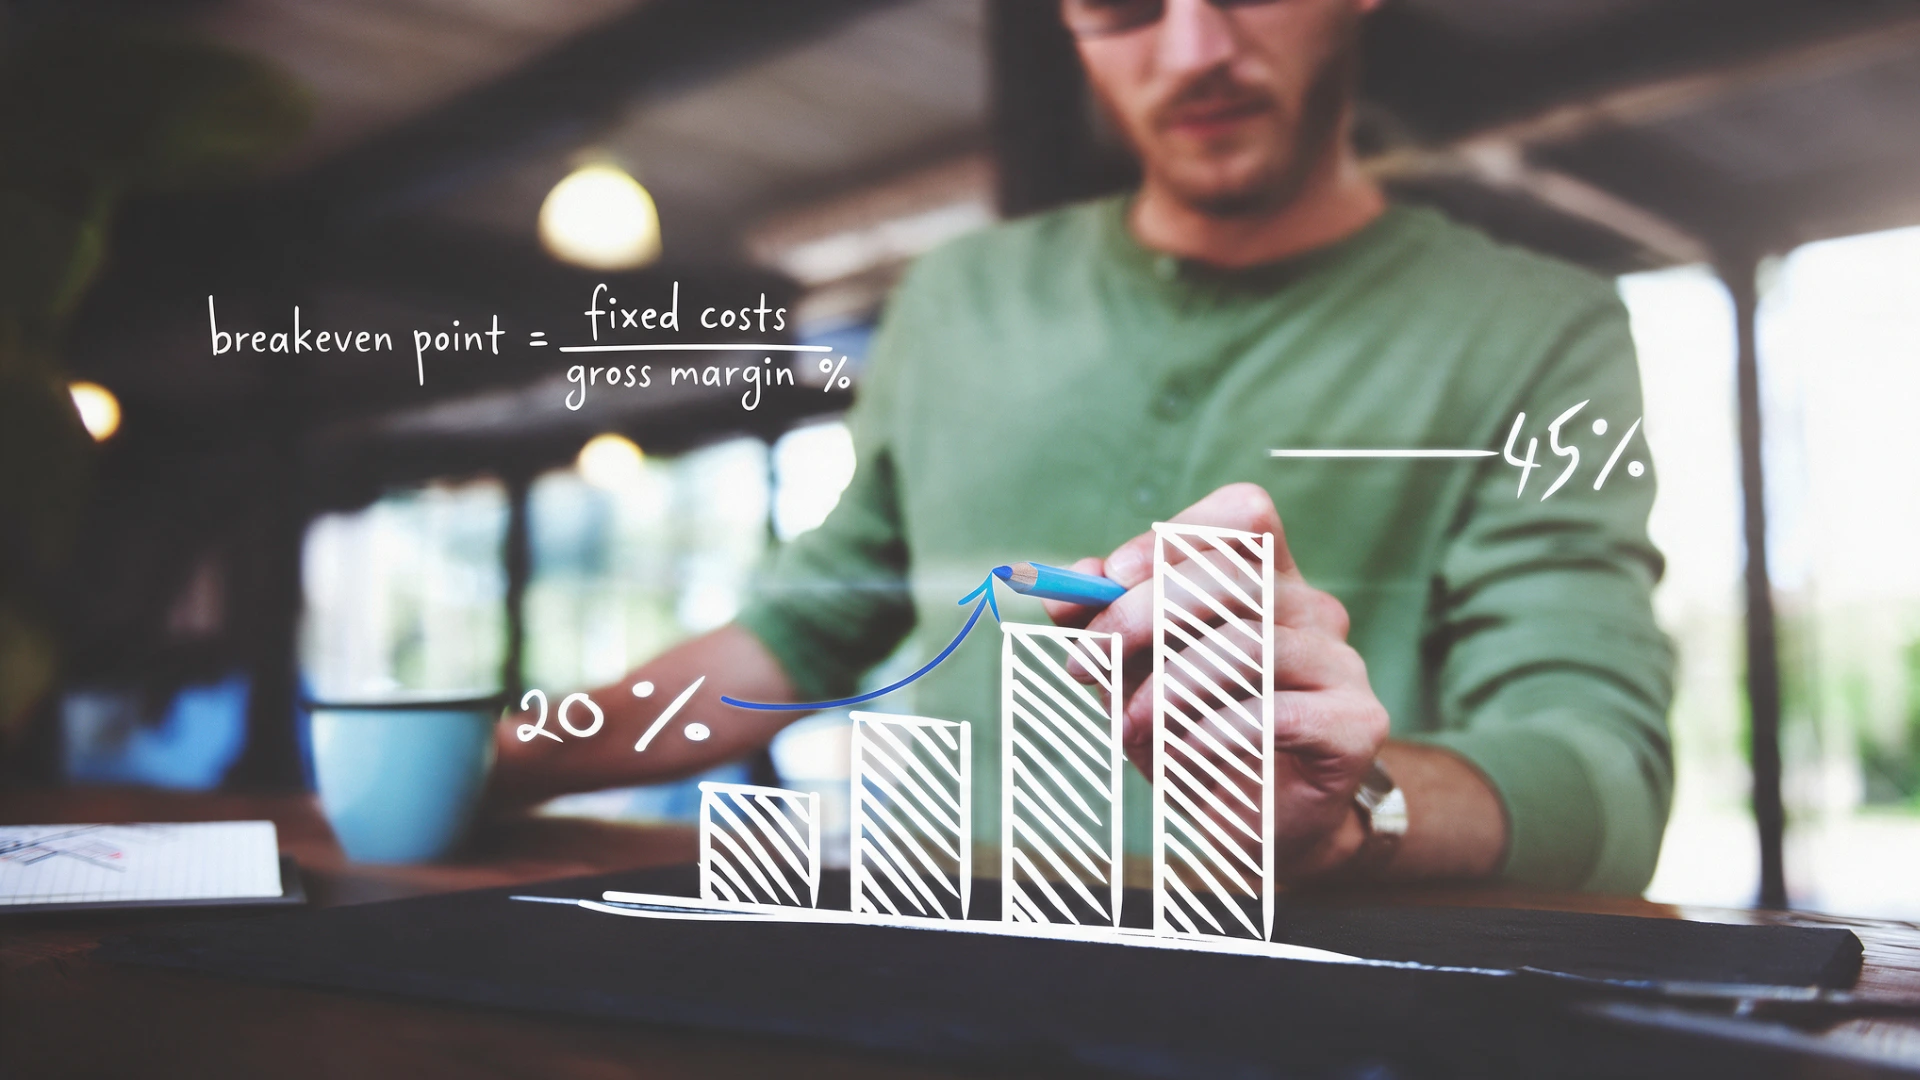
The textbook breakeven is calculated by dividing your fixed costs by gross margin percentage. If your overheads are $28,000 a month and you make 40 cents in the dollar, you need $70,000 of sales to break even on paper.
But the textbook breakeven doesn’t tell the whole story. The number you actually need is your cash breakeven.
This number takes into account your fixed costs, removes depreciation, then adds the costs that don’t appear in your P&L, such as loan principal repayments, income tax instalments and the drawings you need to live on.
Ensure you work in GST-exclusive figures throughout, on both costs and sales, or the whole map will be out by up to 10%.
In our experience, for most of the businesses we work with, cash breakeven sits 15 to 30 percent above the textbook figure. This is one of the reasons a business can show a profit, but still not have enough cash to pay itself.
Breakeven is not one number for the year
This is the part almost everyone misses.
Your breakeven moves, and sometimes dramatically. But it usually moves for reasons you can predict months ahead. One recent change has lifted the baseline permanently, and then there are the months to watch.
Payday super: a permanent shift, not a spike
Since 1 July 2026, super must reach your employees’ funds within seven business days of each pay run, rather than 28 days after the end of the quarter.
Your annual super cost hasn’t changed. What has changed is that it now leaves the bank every pay run instead of four times a year. That lifts your weekly cash requirement permanently and removes a quarterly spike you may have been planning around. If you’re still budgeting on the old quarterly rhythm, your weekly number is too low.
With that in the baseline, here are the months where your breakeven actually moves.
BAS months
In the months a quarterly BAS is due, you need to fund a quarter’s GST and PAYG instalments on top of your usual expenses. That means your cash breakeven is higher in those months. For businesses paying BAS quarterly, this typically means four months a year when your cash requirements are higher. If you lodge monthly, the effect is smaller but it lands every month.
Trading days
January, Easter and the Christmas shutdown give you fewer days to earn the same fixed costs. Meanwhile, your rent, wages and other regular expenses don’t necessarily reduce. A month with 18 trading days instead of 22 carries the same rent.
Annual lumps
Some costs only come around once or a few times a year, such as insurance renewals, WorkCover, licence fees, software subscriptions or vehicle registrations. These costs usually cluster, and when several of them land in the same month, they can create a significant jump in the cash your business needs.
Mapping them early means you can plan for these extra costs rather than being caught off guard.
1 July: the new financial year
Award increases, wage reviews and rent reviews often land together at the start of the new financial year. Award increases take effect from the first full pay period on or after 1 July, which is often a week or two later than owners expect. Once these costs increase, they can permanently lift your business’s baseline costs and, in turn, your breakeven point.
Map it, month by month
Knowing that your breakeven point can change is one thing. The useful part is knowing when it’s going to change. That’s where a month-by-month cash flow map can help.
Create 12 columns, one per month, with your cash breakeven in one row, realistically expected sales beneath it and the gap below that.
You’re looking for the months where your expected sales fall below your cash breakeven. These aren’t always the months you’d expect.
A business can have a strong October and still run out of money if that’s when the BAS, an insurance renewal and a quiet trading fortnight all arrive at once.
Then do something with it
Once you can see the months when your cash breakeven is higher, you can plan ahead rather than waiting for those months to put pressure on your cash flow.
- Pre-fund the higher breakeven months. If you know some months will require more cash than others, use the stronger months to build up a buffer. A good month isn’t a windfall; it’s the deposit on a bad one.
- Push discretionary spending into lower breakeven months. If you have flexibility around when to make purchases, hire staff or run a marketing push, consider timing them for months when your cash breakeven is lower.
- Bring the number down to a target your team can act on. Instead of telling your team you need to make $850,000 over the year, break it down into something more useful. “We need $16,400 a week” or “we need 11 jobs a month” beats an annual figure nobody remembers.
- Test what happens when your margin changes. If your gross margin drops by three points, work out how much extra revenue you’ll need to make to cover the difference. It’s usually a confronting number, but it can show you just how much a small change in revenue can affect the amount you need to sell.
What we suggest
Knowing your breakeven point helps you make better decisions, but knowing when it peaks helps you make them at the right time.
Want to know what your breakeven looks like month by month? Get in touch with Business + Numbers and we can help you map out your next 12 months. It’s a short piece of work and you might be surprised by which month puts the most pressure on your cash flow.
This article provides general information only. It doesn’t take your specific business circumstances into account. Please talk to us or your accountant before acting on any of the information provided.